
The new Haitian Tax Code comes into effect
By NAGO News
2 min read
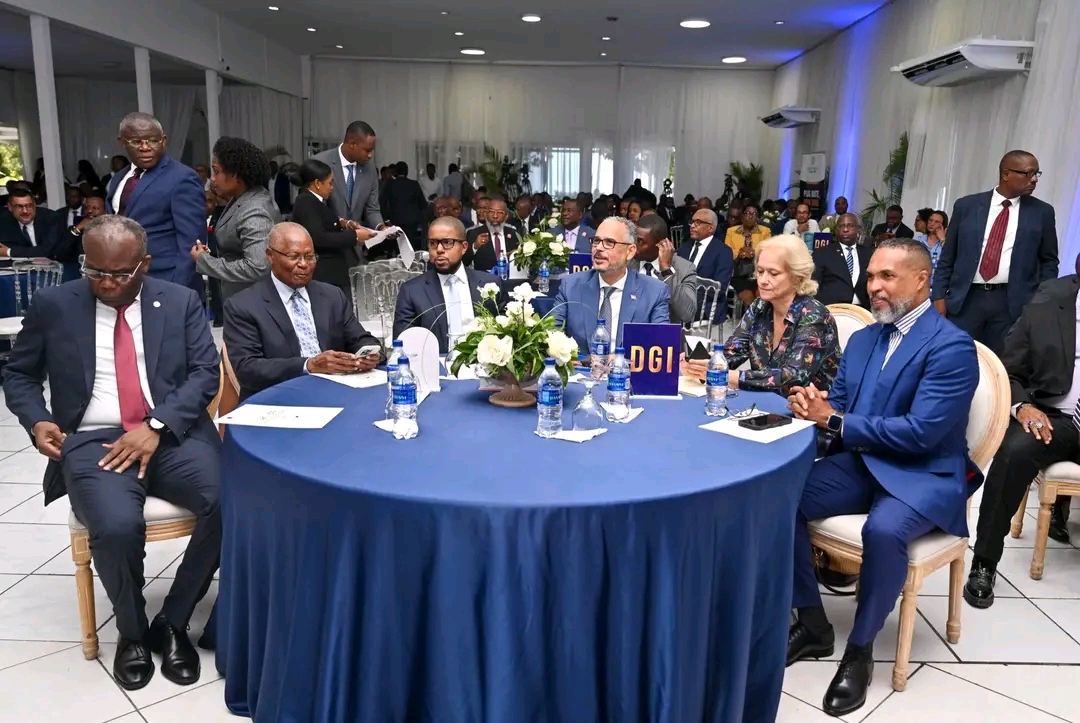
Prime Minister Alix Didier Fils-Aimé officially launched the new Haitian Tax Code on Thursday, October 1st, at the reopening of the fiscal year 2026-2027. This code aims to harmonize and simplify tax provisions scattered across several laws and regulatory texts.
In his speech, Fils-Aimé emphasized that the new fiscal framework must make rules clearer to strengthen taxpayer confidence. The Minister of Economy and Finance, Serge Gabriel Collin, also stressed the importance of this reform for improving public finance management.
The General Tax Directorate (DGI) is responsible for the strict application of the Code. Director General Chesnel François called on his agents to master the new provisions and modernize their information systems to improve service quality for taxpayers.
What the text published in Le Moniteur says
The decree, published in special issue 48-A of Le Moniteur dated 30 September 2026 and posted online by the DGI, replaces the Tax Code of 19 December 2022. It brings the General Tax Code and the Book of Tax Procedures together in a single text of 543 articles. The text justifies governing by decree by the absence of a functioning Parliament.
Under Article 540, the Code has been in force since 1 October 2026; the details of its application will be set by decisions of the Minister of the Economy and Finance. Article 541 abolishes every tax, duty and levy that was not carried over into the new Code.
Some of the rates written into the text:
- income tax (Article 132): 0% up to 360,000 gourdes a year, 12% from 360,001 to 540,000, 18% from 540,001 to 1,080,000, 25% from 1,080,001 to 2,160,000 and 30% above that;
- corporate tax (Article 137): 30%, and 10% for savings and credit cooperatives;
- turnover tax (TCA, Article 186): 10%;
- flat-rate regime for industrial and commercial profits: 5% for services, 2% for other activities;
- 10% withholding on rent paid by the State, legal entities and businesses, except when the landlord is itself a taxable business;
- travel tickets (Article 213): a 10% tax on tickets issued in Haiti, or issued abroad for a Haiti resident whose final destination is Haiti;
- telecommunication services: a 2.5% duty.
Articles 537 and 538 bar any public official from granting a tax remission or reduction outside the cases set by law, and void any contract clause granting an exemption that contradicts the Code.
2025-2026 income: the old scale
In a notice dated 21 October, the DGI points out that the old income tax scale still applies to income earned in fiscal year 2025-2026, because the law is not retroactive. The final return for that income is filed between 1 October 2026 and 31 January 2027. The new scale applies to wages from October 2026.
Videos
Watch now.
Reporting by DGI — Décret portant Code fiscal (Moniteur spécial 48-A)
Comments 0